CPOS: Tap to Pay Card Reader

Screenshots
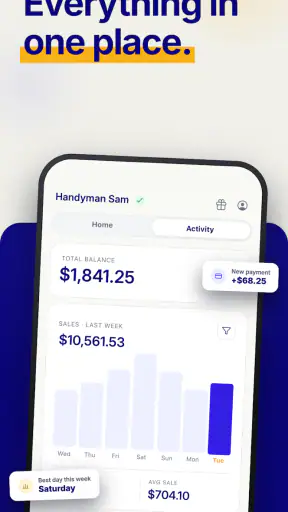
Details
- Rating
- 155.00 reviews
- Version
- 2.34.0
- Developer
- CPOS
Analysis by Norviv
I approached CPOS: Tap to Pay Card Reader as someone who wanted to accept a card payment without carrying a separate terminal. That starting point matters, because this is not a full accounting suite or a replacement for every point-of-sale system. It is a focused business app from CPOS that turns a compatible phone into the place where a customer can tap a card or supported payment device. In the right situation, that can remove a surprisingly awkward part of taking payment.
The app is free, rated for Everyone, and sits in the business category. It has reached over ten thousand installs, with an average rating of 4.4 from more than two hundred ratings and over one hundred reviews. Those figures suggest a useful level of interest, although I would still treat the app as a payment tool to test carefully in my own workflow rather than something to adopt blindly because of its rating.
My overall impression is that CPOS makes the most sense for independent sellers, mobile service providers, small teams, and occasional businesses that need a compact way to receive card payments. The appeal is obvious: fewer devices to carry and no separate monthly hardware commitment described in the app’s store summary. The trade-off is equally important: a phone-based reader depends on the phone, its compatibility, its connection, and the payment process being properly prepared before a customer is standing in front of you.
What to expect before taking a payment
The first thing I would clarify is what this app is designed to do. CPOS is a phone-based card reader, not simply a digital cash register. Its central job is to let the phone participate in a contactless payment interaction. That makes it especially interesting for businesses that work away from a fixed counter, such as a market seller, a visiting professional, or someone collecting payment after completing a service.
I would not expect it to automatically solve stock control, invoicing, staff permissions, customer management, or detailed business reporting. Those needs may require another tool or a broader point-of-sale system. CPOS can be valuable precisely because it concentrates on the payment moment, but that narrow purpose also means I would assess it against the way I already record sales and reconcile money.
The app’s current version is 2.34.0, and it requires Android 8.0 or later. That is worth checking before planning a busy sales day around it. A phone that is technically old enough may still offer a less comfortable experience if its battery is weak, its system is unstable, or its contactless hardware is unavailable. For a first test, I would use the actual phone intended for work rather than assuming another device will behave the same way.
There is also a difference between “the phone can read a tap” and “the whole payment workflow is ready.” A successful setup normally involves more than installing an app. You need to understand how a transaction is started, how the customer presents a card or device, and how you will recognize that the payment has finished. I would learn that sequence before trying it with a queue of customers.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Who benefits most from this format
I see the strongest fit for someone who takes payments in changing locations. A craft seller can keep one phone at a stall instead of bringing a dedicated terminal. A mobile technician can finish a job, enter the amount, and handle payment without asking the customer to use cash or wait for an invoice. A small organization collecting occasional fees may also appreciate not having another piece of equipment to store and charge.
It can also suit a business that already has separate tools for receipts, appointments, or bookkeeping. In that case, CPOS can be treated as the payment step rather than being forced to become the center of the entire operation. That separation is useful, but it means I would create a simple habit for matching each payment with the related order or service.
I would be more cautious if you run a busy shop with several employees, complicated product variants, refunds, or strict reporting requirements. A dedicated point-of-sale system may be better when you need a register, inventory, staff controls, printed receipts, and detailed end-of-day reports in one place. CPOS may still handle the tap itself, but the surrounding administrative work could become inconvenient if you expect one small app to manage everything.
Getting ready without making the first customer your test
My recommended setup starts with a quiet test rather than a live sale. Install CPOS on the phone you intend to use, check that the device meets the Android requirement, and look through the payment flow slowly. I would keep the phone charged, remove unnecessary distractions from the workspace, and make sure the screen is easy to see in the lighting where payments will happen.
Before accepting money, I would also decide how amounts are prepared. Entering a price while a customer is waiting creates avoidable pressure, especially if the sale includes several items or a service adjustment. A short written price list, a separate order screen, or a calculator can reduce mistakes. The reader should be the final payment step, not the place where you are still trying to reconstruct what the customer bought.
One practical tip is to establish a confirmation routine. After the customer taps, I would wait for the app’s clear completion state before moving on, then record the sale in whatever bookkeeping or order system I use. I would not rely only on the customer’s phone animation or a sound. The person paying may see a bank notification even when the merchant-side process still needs attention, so both sides should know which signal counts as completion.
Another useful habit is to prepare a fallback before the first day. That does not mean assuming CPOS will fail; it means recognizing that a phone can lose power, become unavailable, or be unsuitable for a customer’s preferred payment method. A backup payment option, an alternative device, or a clear way to arrange payment later can prevent a technical interruption from becoming an uncomfortable conversation.
I would also separate testing from accounting. A test transaction should be clearly identified so it cannot later be mistaken for a real sale. If you are using CPOS for a business, make sure the person responsible for records knows how a completed payment will be recognized and where the transaction details will be checked. The app may make the tap simple, but reconciliation still depends on a disciplined process.
Questions I would settle before launch
Can the intended phone actually be used for contactless payments? Does the operating system meet the minimum requirement? Is the phone comfortable to hand toward a customer without exposing unrelated information? Can you see the payment result clearly in your usual environment? These are simple questions, but answering them at home is far better than discovering the problem at a market stall.
I would also consider who controls the device. If several people use the same phone, the business needs a clear handover routine. If the phone belongs to a staff member, the owner should know how the app fits into the sales record. A payment reader can be technically easy while still creating confusion about responsibility.
The app is free, which lowers the barrier to trying it. I would still distinguish between the cost of downloading an app and the broader cost of operating a payment process. Time spent checking transactions, handling exceptions, and keeping records matters. The absence of a hardware purchase or monthly fee in the store summary is attractive, but it should not replace a proper look at the payment terms and business requirements that apply to your situation.
The first successful action: keep it deliberately simple
For my first meaningful use, I would choose one straightforward sale with a known amount and no complicated changes. I would open the payment flow before handing over the phone, confirm the total, and tell the customer exactly what to do: bring the contactless card or supported device near the phone when prompted. Clear instructions reduce the chance that the customer taps the wrong area or moves away too quickly.
The best first success is not merely seeing a card touch the phone. It is completing the entire loop: prepare the amount, accept the tap, recognize the finished state, and connect the payment with the sale record. That last step is the one new users often overlook. A payment that cannot later be matched to an order creates work, even if the tap itself felt effortless.
In an everyday scenario, imagine a mobile dog groomer finishing an appointment at the customer’s home. The groomer already knows the service total, opens CPOS on the work phone, and lets the customer tap. Once the app confirms the result, the groomer marks the appointment as paid in the separate booking or records system. The value here is not a flashy feature; it is removing the need to carry a dedicated reader from house to house.
A market seller could use a similar routine, but the environment changes the priorities. Bright sunlight, noise, a moving queue, and a phone held in one hand make confirmation easier to miss. I would position the phone so both people can see it, say the amount aloud before the tap, and pause long enough to verify completion. That small communication habit is more important than trying to make the transaction feel rushed.
One non-obvious advantage of a phone reader is flexibility in where the payment happens. You can bring the reader to the customer rather than making the customer lean across a counter. That can be helpful for accessibility and for services delivered in homes or outdoor locations. The trade-off is that the phone becomes part of the customer interaction, so keeping the device clean, charged, and dedicated to the task becomes part of professional presentation.
How I would handle a payment that seems stuck
If a transaction does not appear to finish, I would avoid immediately repeating the tap or starting a second payment. First I would check the state shown on the merchant side and ask the customer whether their bank app shows a completed or pending attempt. Repeating too quickly can create uncertainty about whether the customer might be charged twice. The safest response is to slow down, identify the actual state, and follow the app’s on-screen process.
This is also why I would not use CPOS for a major event without a rehearsal. A busy setting magnifies small misunderstandings: the customer may tap before the amount is ready, the seller may move to the next person too quickly, or a weak connection may make the result unclear. Practicing the sequence with a colleague helps everyone learn what “finished” looks like.
For refunds, cancellations, or disputed payments, I would expect to consult the relevant transaction records and the payment service’s procedures rather than improvising inside the tap screen. A reader can make acceptance convenient without making every after-sale case equally simple. If your business handles frequent returns, this is one area where a more complete point-of-sale system may save time.
Common confusion and the limits I noticed
The most likely confusion is treating “no hardware” as “no setup.” The phone is the hardware. Its operating system, contactless capability, battery, screen, and general condition all affect the experience. CPOS reduces the equipment you carry, but it does not remove the need to choose a suitable device and prepare it for repeated use.
Another confusion is assuming that every customer can pay in exactly the same way. Contactless card acceptance is convenient, but a customer may prefer another method or may have a card or device that does not work in the expected manner. I would present CPOS as one payment route, not as a promise that every possible payment situation will be handled by one tap.
The phone’s personal nature can also create friction. On a shared personal device, notifications, calls, and unrelated apps can interrupt the moment. Even without adding another device, I would use a work-focused phone where possible, keep the payment screen visible, and avoid switching between applications while a transaction is in progress. This is a workflow recommendation rather than a special feature, but it makes the app feel much more dependable.
Privacy and customer confidence deserve attention too. A customer is handing payment information near a phone that may contain personal content. I would avoid displaying unrelated notifications, keep the device under the seller’s control, and explain the action plainly. The simpler and more transparent the interaction feels, the easier it is for a first-time customer to trust it.
There is also a practical bookkeeping limitation when using a focused reader alongside other tools. If CPOS handles the tap but your invoices, appointments, and inventory live elsewhere, you need a consistent reference method. I would use the same order identifier or customer note across systems where appropriate. Without that habit, a low-friction payment can produce a high-friction reconciliation task later.
When another option is the better choice
I would choose a traditional dedicated terminal when the business needs a device that remains at a counter, is shared by staff, and is built into a broader checkout routine. A full point-of-sale platform is a better fit when inventory changes constantly, several employees need controlled access, or management depends on detailed sales reports. CPOS is more compelling when portability and simplicity matter more than an all-in-one register.
I would also hesitate to rely on it as the only option for a high-volume operation until the complete workflow had been tested under real conditions. The app’s free entry point makes experimentation easier, but a business should not confuse easy installation with guaranteed suitability for every operating environment. Start with a controlled use case, measure the administrative effort for yourself, and expand only when the process remains clear.
For occasional sellers, however, the balance can be favorable. Buying or maintaining a separate terminal may feel excessive when payments are infrequent. A phone-based approach can be a practical middle ground, provided the seller is comfortable with the preparation and has a fallback for interruptions.
My next-step recommendation for a first-time user
I would begin by installing CPOS on the intended Android phone and checking the device before planning any real sales. Then I would perform a complete rehearsal: prepare a known amount, start the payment, practice the customer instruction, verify the completion state, and record the result in the business’s normal system. The goal is to make the first real transaction feel routine rather than experimental.
After that, I would use it for a small number of simple payments and review the parts that happen outside the tap: matching transactions, handling unclear outcomes, and keeping the phone ready. Those observations will tell you more than the installation experience alone. If the app fits your work, its main benefit is the reduction in equipment and setup around mobile payments.
My final view is positive but deliberately practical. CPOS is a focused business app that can make sense for people who need to accept contactless card payments from a phone, especially when carrying a separate reader is inconvenient. Its free price and compact format make it approachable, while the Android 8.0 minimum keeps the initial compatibility check straightforward. I would recommend it to a small or mobile business that wants to test a simpler payment workflow and is willing to maintain good records.
I would skip it as a sole solution if you need a complete retail management system, complex employee controls, or a heavily automated back office. For everyone else, the sensible path is to start small, confirm the phone works in the real environment, and build a clear routine around every completed payment. Used that way, CPOS: Tap to Pay Card Reader feels less like a replacement for an entire checkout operation and more like a useful, portable payment tool.
Frequently Asked Questions
01What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept contactless card and digital-wallet payments using a compatible smartphone or tablet. Instead of requiring a separate card terminal, the app uses the device’s NFC capability to process supported tap-to-pay transactions. Availability and supported payment methods may depend on your country, provider, device, and merchant account.
02What devices are compatible with CPOS: Tap to Pay Card Reader?
Compatibility generally depends on whether your Android or iOS device supports NFC, meets the app’s operating-system requirements, and is approved by the payment service. You may also need a compatible merchant account and a device with security features such as a screen lock. Before downloading, check the official store listing and CPOS documentation, because supported models, regions, and operating-system versions can change over time.
03Can I accept all debit cards, credit cards, and digital wallets with the app?
CPOS: Tap to Pay Card Reader is intended for contactless payments, but it may not accept every card or wallet in every market. A customer’s card must support contactless transactions, while the payment network and wallet must be enabled by the service provider. Transaction limits, supported brands, currencies, and local regulations can also affect acceptance, so businesses should confirm the available payment methods before relying on the app.
04Is CPOS: Tap to Pay Card Reader safe for business transactions?
The app is built for point-of-sale use and typically relies on encrypted payment processing, device security, and the safeguards provided by its payment provider. However, security also depends on how the business protects its phone, account credentials, and staff access. Use a strong device passcode, install updates, avoid rooted or compromised devices, and review transaction confirmations carefully. No payment solution can eliminate every security or fraud risk.
05Are there fees or additional requirements for using CPOS: Tap to Pay Card Reader?
Downloading the application may not be the only cost involved. Businesses can be charged transaction processing fees, subscription or service fees, or other charges determined by the CPOS provider or payment processor. Registration, identity verification, a merchant account, internet access, and supported hardware may also be required. Review the current pricing, terms, refund policy, and regional requirements before activating the service for customers.


